
Bitcoin regulation is moving in opposite directions across two major economies. In the United States, regulators and exchanges have widened access to Bitcoin-linked derivatives and options. In India, central-bank and tax officials are pressing for tighter barriers around crypto exposure, even though the government has not enacted a nationwide prohibition. The contrast has generated a clearer reaction in exchange-company shares and regulatory risk pricing than in Bitcoin itself, whose price continues to respond to global liquidity, macroeconomic expectations, positioning and broader risk sentiment.
What changed in the United States
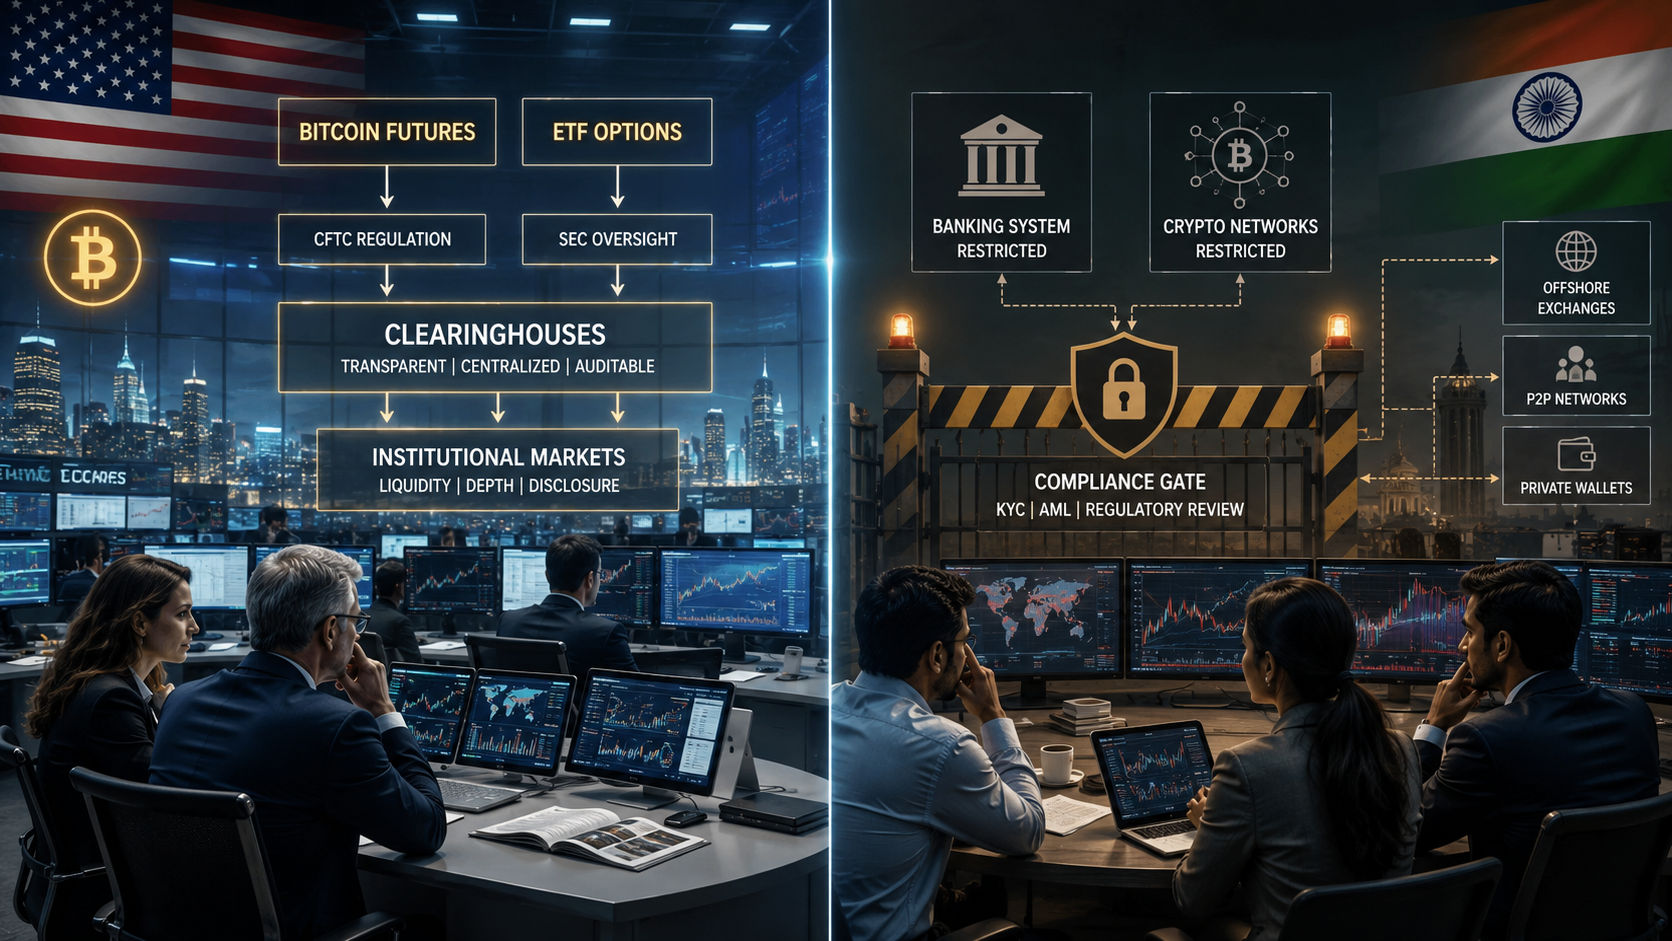
The most important recent U.S. event occurred on May 29, 2026. On that date, the Commodity Futures Trading Commission announced approval of KalshiEX's BTCPERP contract, a perpetual futures contract referencing the spot price of Bitcoin. Kalshi had submitted the product for review one day earlier, on May 28. Unlike conventional futures, perpetual contracts do not have a fixed expiration date. A funding mechanism is used to keep their price aligned with the underlying reference market.
The approval mattered because perpetual futures had historically been concentrated on offshore crypto venues. The CFTC decision brought a formally approved version of the structure onto a U.S.-regulated designated contract market. A separate CFTC staff letter issued on May 29 also addressed how certain perpetual contracts offered through foreign boards of trade could be categorized under existing rules. Coinbase said the same day that U.S. clients could access global crypto perpetuals and options on futures through its CFTC-regulated futures commission merchant.
The expansion did not stop with perpetuals. On July 15, the Securities and Exchange Commission published notice of an immediately effective NYSE Arca rule change proposing to raise the position and exercise limits for options on the iShares Bitcoin Trust ETF, or IBIT, from 250,000 to 1,000,000 contracts on the same side of the market. The filing said comparable increases had already been approved or made effective on other options exchanges. This does not change Bitcoin's protocol or create new coins, but it expands the capacity available for hedging, market-making and complex options strategies around a spot-Bitcoin ETF.
The clearest immediate market response appeared in the shares of traditional exchange operators. Reuters reported on June 2—four days after the CFTC approval—that Cboe Global Markets fell 9%, while CME Group and Intercontinental Exchange each declined roughly 4%. Investors were weighing both the risk profile of perpetual futures and the possibility that the structure could later spread into equities or commodities, increasing competition for incumbent exchanges.
That reaction illustrates why a regulation described as "crypto-friendly" can produce mixed winners and losers. Crypto platforms may gain access to products that previously drove activity offshore. Traditional exchange groups may face fee pressure or a need to accelerate their own offerings. Market makers and sophisticated traders gain more instruments for hedging and relative-value strategies, but greater leverage can also amplify liquidations and short-term volatility when positions become crowded.
The expansion is also legally contested. CME's Chicago Mercantile Exchange sued the CFTC in June, arguing that the agency's treatment of perpetual contracts was improper. Reuters reported on July 6 that the lawsuit remained active despite a change in CME's legal representation. Until the court resolves the dispute—or the parties change course—the durability and possible extension of the framework remain uncertain.
India is moving toward tighter separation from regulated finance
India's direction became clearer through documents reported by Reuters on July 8. The documents themselves were dated in May and June, so the policy position preceded the publication date. According to the report, the Reserve Bank of India again argued for a policy "leaning towards prohibition" and said banks and financial institutions should be prevented from holding, trading or gaining exposure to crypto assets and privately issued stablecoins.
The tax department raised a different concern: activity routed through offshore exchanges and private wallets can be difficult to identify and assess for tax compliance. Its estimates indicated that nearly 39 million Indian crypto traders held about $2.1 billion in digital assets at the end of May. Those figures describe reported holdings, not a measure of daily trading volume or the full economic exposure of Indian users.
India has not, however, enacted a comprehensive crypto ban. The country already applies a 30% tax to gains from transfers of virtual digital assets, with applicable surcharge and cess, and requires virtual-asset service providers to register with the Financial Intelligence Unit as reporting entities. This creates a restrictive operating environment without fully eliminating crypto ownership or trading. The latest documents suggest that influential agencies want to keep crypto outside the core banking system, but the final government policy has not been published.
Why Bitcoin's reaction is harder to isolate
There is no reliable basis for attributing a sustained Bitcoin move solely to either development. U.S. product expansion can support access, liquidity and price discovery, but it can also increase leverage and make the market more sensitive to forced liquidations. India's proposed restrictions could reduce local banking connectivity or raise compliance costs, yet no nationwide ban has been enacted and the reported value of Indian holdings is small relative to the global Bitcoin market.
For forex traders, the regulatory split is best treated as a cross-market risk factor rather than a direct currency signal. A rapid increase in crypto leverage can affect broader risk appetite, exchange equities and demand for U.S. dollar liquidity. Indian restrictions could influence local payment channels, offshore flows and sentiment toward technology assets, but they do not automatically imply a predictable move in USD/INR or other currency pairs. Interest-rate expectations, energy prices, capital flows and central-bank policy remain more direct drivers of foreign-exchange markets.
What remains unknown
- U.S. litigation: CME's challenge could narrow, delay or overturn parts of the CFTC approach, although the outcome and timetable are uncertain.
- Product adoption: Regulatory permission does not guarantee deep liquidity, stable funding rates or broad customer demand.
- Leverage risk: Perpetual futures can expose users to margin calls, funding costs and automatic liquidation, especially during sharp price moves.
- India's final policy: The RBI's preference is influential but is not itself a statute. The government could choose prohibition, limited regulation or continued reliance on tax and anti-money-laundering rules.
- Cross-border migration: Tighter domestic restrictions may move activity offshore rather than eliminate it, making supervision and tax collection more difficult.
Bottom line
The United States is building a wider regulated market around Bitcoin, while India is considering stronger barriers between crypto and its formal financial system. The immediate market signal has been competition and legal uncertainty among exchanges, not a clean one-directional move in Bitcoin. Traders should distinguish an approved product from proven adoption, and a central-bank recommendation from enacted law. The split may shape where liquidity, derivatives activity and compliance costs concentrate, but it does not remove Bitcoin's volatility or create a dependable price outcome.
This article is for informational purposes only. It is not financial advice, a trading signal, a personalized recommendation or a promise of returns.