
Global markets entered the final week of July with two unusually large headlines competing for attention: a new 50% U.S. tariff on selected Canadian goods and a Japanese yen trading near its weakest level against the dollar in four decades. The two developments appeared at the same time, but investors did not treat them as one unified shock. The tariff announcement produced a visible but contained reaction in Canadian currency and bond markets, while the yen's slide reflected a broader combination of dollar strength, higher energy costs, monetary-policy divergence and doubts about Japan's policy credibility.
That distinction matters for forex traders. The 50% levy is not a tariff on Japan, and there is no verified evidence that it directly caused the yen to reach its multi-decade low. Instead, the market reaction shows how different risks are transmitted through currencies: trade restrictions can pressure the currency of the targeted economy, while a currency already weakened by rates, import costs and domestic policy concerns may fail to benefit even when global uncertainty rises.
Two Headlines, Two Different Market Channels
On July 20, 2026, the White House announced additional tariffs of 50% on certain Canadian products under Section 338 of the Tariff Act of 1930. The administration said the action responded to what it described as discriminatory Canadian treatment of U.S. products. Reuters, in a report published July 20 and updated July 22, said the measure covered nearly $20 billion of imports, including products such as wine, cement, dairy goods, hockey equipment, furniture and clothing. The new duties were scheduled to take effect on August 19, leaving a 30-day period in which negotiations or implementation details could still change.
Canada disputed the U.S. position. In a statement dated July 20, Prime Minister Mark Carney described the move as another unilateral trade action and said Canada remained prepared to negotiate. This means the confirmed event was the announcement of the tariff plan; the final economic impact was still uncertain because the duties had not yet entered into force as of July 29.
The yen story developed through a separate sequence. On July 21, the currency weakened beyond 163 per U.S. dollar for the first time in roughly 40 years. On July 23, it touched 163.98, its weakest level since November 1986, according to Reuters. By July 29, it had recovered modestly to around 163.38, but remained close to the four-decade low as markets waited for decisions from the Federal Reserve and the Bank of Japan.
The Immediate Tariff Reaction Was Concentrated in Canada
The clearest first response to the tariff announcement came from the Canadian dollar. On July 21, the loonie weakened 0.2% to 1.4104 per U.S. dollar, its lowest level in one week. Canadian government bond yields also fell, and the gap between Canadian and U.S. two-year yields widened to its largest level since May 2025. Traders reduced expectations for Bank of Canada rate increases, reflecting concern that new trade barriers could weaken Canadian growth and give the central bank less room to tighten policy.
The broader global reaction was comparatively restrained. A Reuters market review published July 21 said world equities rallied as semiconductor shares outweighed concerns about the renewed trade dispute, rising oil prices and geopolitical tension. The report described the market response to the Canadian tariff announcement as limited, partly because investors viewed the 30-day implementation window as an opportunity for negotiation rather than proof of an irreversible breakdown in North American trade.
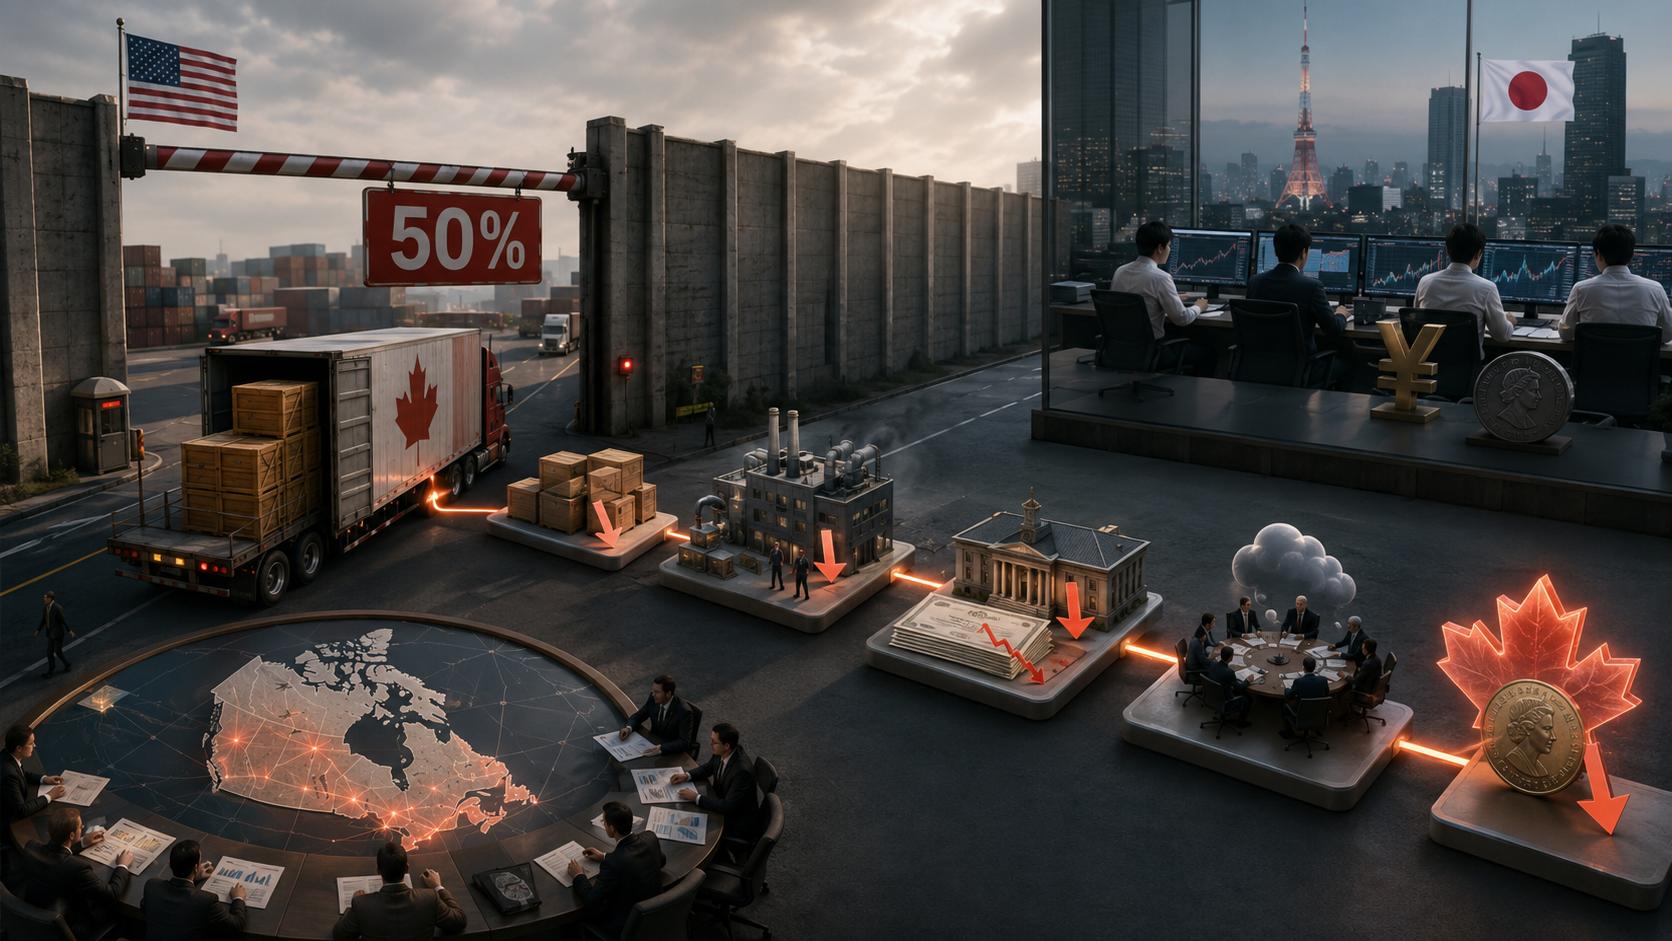
This muted reaction does not mean the tariffs are economically unimportant. A 50% duty is large enough to disrupt pricing, orders and supply chains for affected products if it takes effect as announced. However, the covered trade value was a limited share of total U.S. imports from Canada, and the market had not yet received complete evidence about exemptions, retaliation, negotiated changes or how much of the cost companies would absorb. Investors therefore priced a specific Canadian risk premium rather than a full global flight from risk.
Why the Yen Kept Falling During a Period of Uncertainty
The yen is traditionally associated with safe-haven demand, but that relationship is not automatic. In July 2026, several forces were working against it. The U.S. dollar was supported by relatively high Treasury yields and expectations that the Federal Reserve would maintain a restrictive stance. Higher oil prices also hurt the yen because Japan is a major energy importer, increasing the country's import bill and demand for foreign currency. At the same time, markets remained unsure how quickly the Bank of Japan would continue raising interest rates.
The Bank of Japan's policy rate stood around 1.0% after its June move, and its next monetary-policy meeting was scheduled for July 30-31. Even after several steps toward normalization, Japanese rates remained below U.S. rates. That difference continued to support carry trades in which investors borrow or fund positions in lower-yielding yen and hold higher-yielding assets elsewhere. When the dollar and U.S. yields rise, the cost of reversing those positions can make yen weakness more persistent.
Policy credibility added another layer. Reuters reported that investors were concerned about the Japanese government's spending plans and the central bank's cautious pace of tightening. The U.S. Treasury's semiannual foreign-exchange report, released on July 23, said yen weakness had persisted despite a narrowing U.S.-Japan rate gap and described excessive exchange-rate volatility as undesirable. It also argued that further monetary normalization could help anchor inflation expectations and reduce volatility.
These factors explain why the Canadian tariff did not produce a sustained safe-haven rally in the yen. The trade measure was geographically concentrated, markets initially treated it as negotiable, and other forces—oil, yields, the dollar and Japanese policy uncertainty—were more powerful in the USD/JPY market. The yen's decline was therefore not a simple risk-on signal; it reflected Japan-specific vulnerabilities inside a globally defensive dollar environment.
Markets Are Watching Intervention Risk
A yen near levels last seen in 1986 increases speculation that Japanese authorities could intervene by selling foreign currency and buying yen. On July 29, Reuters reported that traders remained alert to that possibility, particularly if the Federal Reserve's communication strengthened the dollar or if the Bank of Japan disappointed expectations for future tightening.
Intervention is possible, but its timing and durability cannot be predicted from official warnings alone. Authorities may focus on the speed and disorderliness of currency moves rather than defend a single exchange-rate level. Any direct action could produce a sharp short-term reversal, but its longer-term effect would likely depend on whether interest-rate expectations, energy prices and confidence in Japanese policy also changed.
What Remains Unknown
The next market phase depends on several unresolved events. First, the Canadian tariffs are scheduled to start on August 19, but the 30-day window allows further negotiations, exemptions or retaliation. Second, the Federal Reserve's July 29 decision and guidance could alter the dollar and U.S. yield outlook. Third, the Bank of Japan's July 30-31 meeting may change expectations for the pace of normalization. Finally, Japanese authorities have not committed to a specific intervention threshold.
For beginner and intermediate traders, the central lesson is to separate simultaneous headlines from direct causation. The 50% U.S. tariff announcement primarily affected Canadian assets because Canada was the target. The yen's four-decade low was driven more directly by interest-rate differentials, higher energy costs, broad dollar demand and uncertainty surrounding Japanese fiscal and monetary policy. Those channels may interact through global risk sentiment, but they are not interchangeable.
This article is for informational purposes only. It does not provide financial advice, a trading signal, a personalized recommendation or any promise about future currency movements.